A BRRR loan and a fix-and-flip loan may both fund acquisition and renovation, but the exit strategy is different. A fix-and-flip loan is usually repaid when the renovated property is sold. A BRRR loan is usually repaid or replaced when the property is rented and refinanced into long-term rental debt. Blue Dot Financial reviews the borrower’s timeline, rehab scope, projected value, rental strategy, and exit plan to determine the right structure. Understanding how BRRR loans work can help investors understand the rental-focused structure.
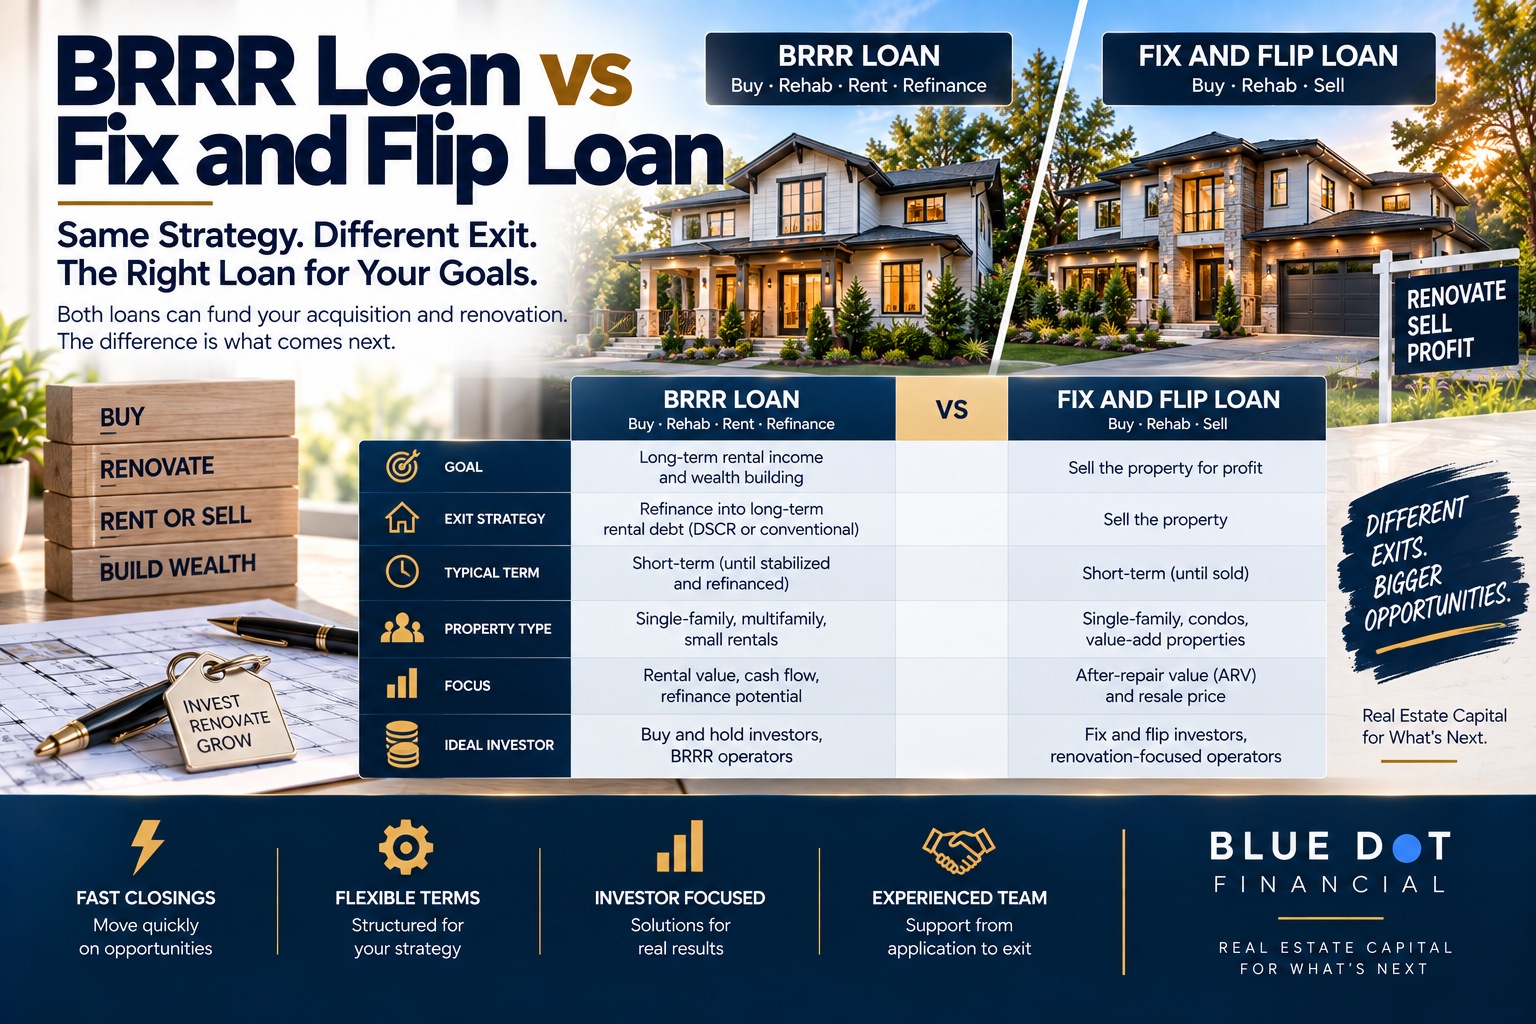
BRRR Loan vs Fix and Flip Loan matters because rental investors need a bridge between acquisition and stabilization. The financing should support the project before the property is ready for long-term rental debt, while still keeping the refinance exit in view from day one. Investors can also review how fix and flip loans work to understand the alternative sale-focused strategy.
This page is written for rental investors, BRRR operators, and landlords acquiring properties that need renovation before stabilization. It is especially useful for borrowers who want to understand whether BRRR loans compared with fix and flip loans can support a non-owner-occupied investment property strategy. Borrowers can also review rehab-to-rent financing when considering renovation projects intended for rental use.
Blue Dot Financial provides private real estate lending for investment projects where speed, collateral clarity, borrower readiness, and exit strategy matter. For BRRR loans compared with fix and flip loans, the review should focus on the asset, the borrower entity, the business-purpose use, the project economics, and the repayment plan. These factors are also part of how private lenders underwrite real estate deals.
BRRR investors often buy properties that are not ready for long-term rental financing on day one. The property may need repairs, occupancy, rent stabilization, or improved value before a DSCR or conventional refinance is available. Short-term private capital can help bridge that gap. Depending on the transaction and timing, bridge loans for real estate investors may also be relevant.
Blue Dot looks at acquisition price, rehab budget, future rental demand, projected value, borrower experience, reserves, and the refinance plan. The exit strategy is central because the borrower usually intends to hold the asset rather than sell it immediately. Investors planning to refinance after stabilization can also review the DSCR refinance exit strategy.
The property should have a realistic path to rent, a clear rehab plan, an achievable refinance value, and enough cash flow potential to support the next loan. The more credible the rental and refinance assumptions, the stronger the request. Investors building or expanding rental holdings can also explore portfolio loans for rental property investors.
This structure may not fit if the property has uncertain rental demand, unclear repair costs, weak refinance options, or a borrower without the reserves to carry the project through stabilization. Borrowers evaluating collateral-focused financing can also review asset-based real estate lending as another way to understand how the property and project economics factor into a loan review.
| Consideration | Why It Matters |
|---|---|
| Collateral | The property or portfolio must support the requested loan amount and exit strategy. |
| Borrower entity | Blue Dot’s borrower-side loans are designed for business-purpose entities, not owner-occupied consumer mortgages. |
| Timeline | Fast closings require complete documentation, clean title coordination, and responsive borrower communication. |
| Exit strategy | Sale, refinance, payoff, or stabilization must be realistic and clearly documented. |
| Reserves | Liquidity helps protect the project from budget overruns, delays, and carrying-cost pressure. |